An investor with anti-dilution protection gets their conversion price adjusted when you raise below the price they paid. Whether that adjustment costs you fourteen percent of the company or half a percent comes down to which of two formulas sits in your term sheet.
Most founders negotiate the wrong one.
What does anti-dilution actually cost founders?
The difference between the two mechanisms can be twenty-eight-fold on the same round.
Take a company with 1,00,000 shares outstanding that raises again, issuing 10,000 new shares at ₹500, below what the earlier investor paid.
Adjusted conversion price | Shares to investor | Founder dilution | |
Full ratchet | ₹500 | ~20,000 | ~14% |
Broad-based weighted average | ~₹955 | ~10,471 | ~0.5% |
Same round, same price, same investor. The only variable is the formula.
What is an anti-dilution clause?
Anti-dilution protects an investor if you later raise at a lower price than they paid, by adjusting the conversion price on their shares so their holding converts into more equity.
An investor who paid ₹100 a share doesn't want their ownership wiped out if you later raise at ₹60. The clause restores roughly the percentage they'd otherwise have lost.
That protection has to be funded by somebody. It comes out of the founders, the employees holding options, and anyone else in common equity.
What is full ratchet?
Full ratchet resets the conversion price completely to the new lower price, regardless of how large the new round was.
If you raised at ₹100 and later take money at ₹60, the earlier investor's whole holding reprices to ₹60. It makes no difference whether the new round was ₹50 lakh or ₹50 crore, because the mechanism ignores volume entirely.
A small bridge does the same damage as a large financing. Full ratchet appears in fewer than 5% of deals, which tells you most investors don't expect to get it.
What is weighted average anti-dilution?
Weighted average moves the conversion price partway rather than all the way, using a formula that weighs the new shares issued against the total already outstanding.
The adjusted price lands between what the investor originally paid and what the new round priced at. The economic pain gets shared rather than transferred wholesale onto common shareholders.
This is market standard in India and elsewhere.
Broad-based or narrow-based?
Broad-based is the founder-friendly variant, and on an ordinary option pool the difference between the two is worth a fraction of a percentage point.
Broad-based counts everything in the denominator: equity shares, preference shares, options, warrants, convertibles, and the unallocated ESOP pool. Narrow-based counts only outstanding preference shares.
A larger denominator produces a higher adjusted conversion price, which means less dilution for you.
What should founders negotiate first?
Refuse full ratchet before arguing about broad versus narrow. The mechanism is worth the fourteen percent above. The formula variant is worth a fraction of a percent.
Founders routinely get this backwards. They spend real leverage on broad versus narrow while full ratchet sits three lines higher in the same paragraph, unchallenged.
Institutional investors at seed or Series A rarely insist on full ratchet, and its presence in a term sheet tells you something about who you're dealing with. It also leaves a mark that outlasts the round, since a full ratchet on your cap table signals to every later investor that somebody wanted unusual protection, making a bridge harder to price when you need one.
Ask for broad-based second, and expect to get it. Standard-form term sheets used in India already default to it. Our guide on negotiating your first term sheet covers what else deserves attention.
How does anti-dilution work in an Indian round?
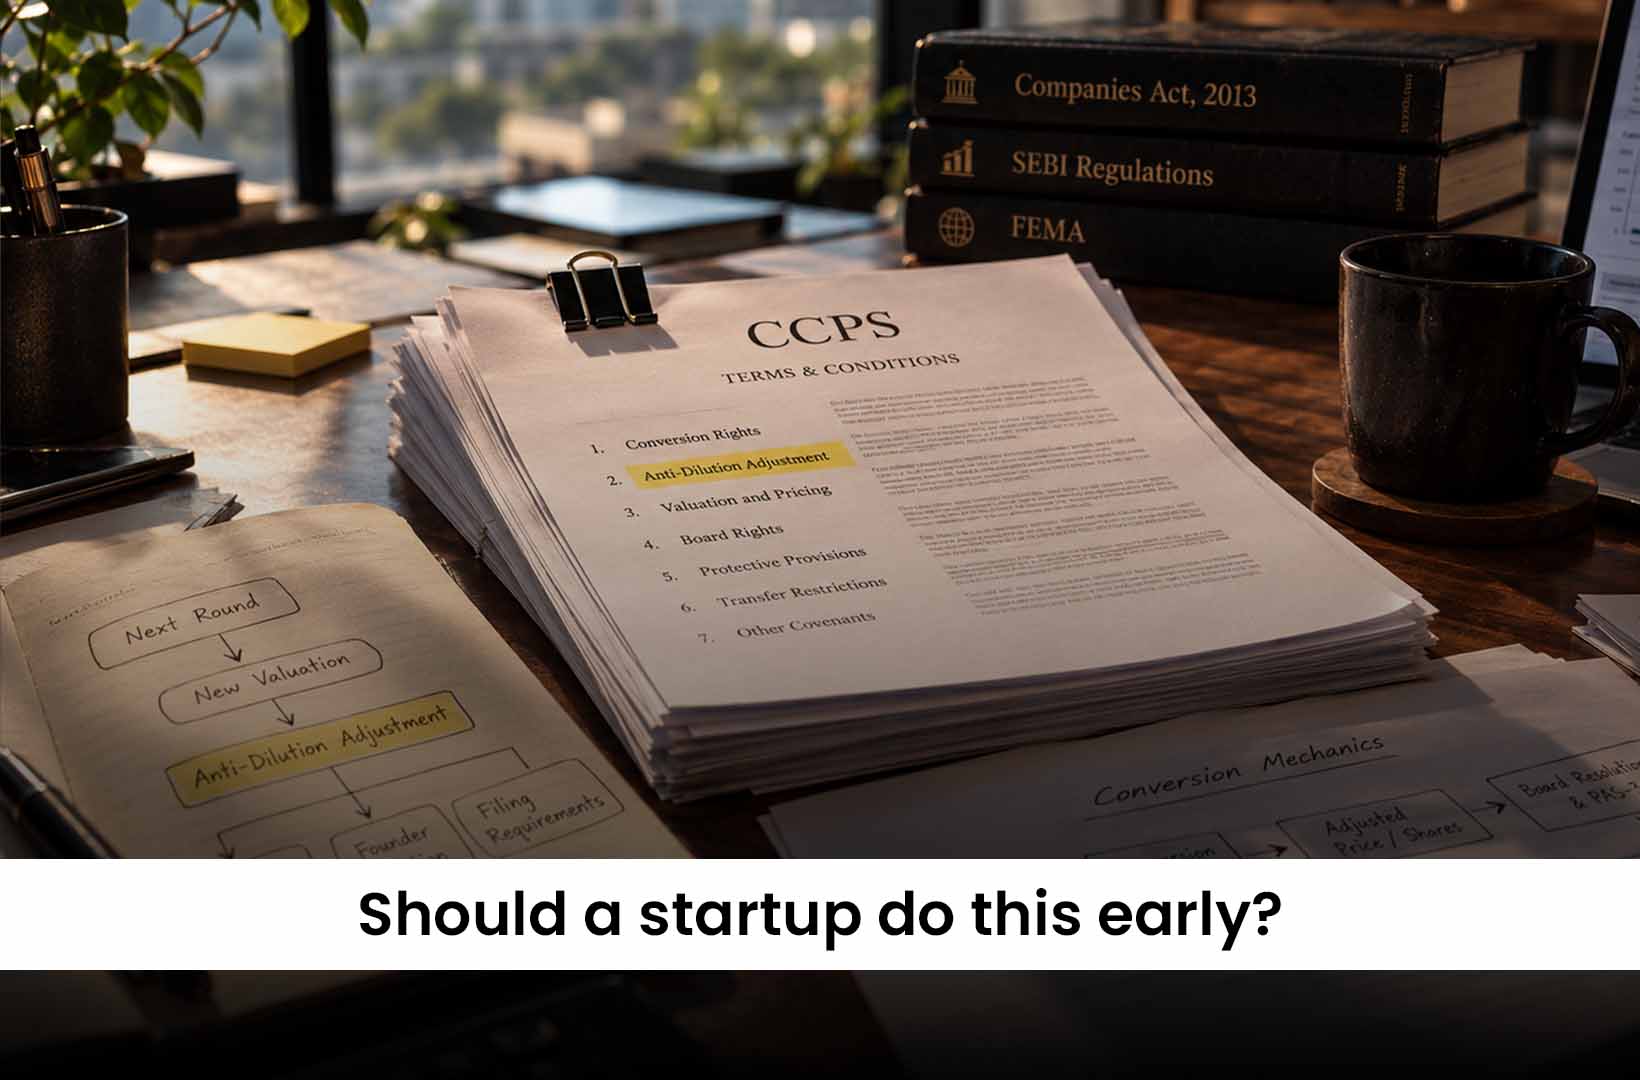
It sits inside the CCPS terms as an adjustment to the conversion ratio, rather than in a separate instrument.
That means the clause interacts with conversion mechanics agreed elsewhere in the same document. Modelling it in isolation gives a misleading answer, so model the instrument rather than the paragraph.
There's a filing consequence people forget. An adjusted conversion still needs its board resolution and PAS-3 filing, and where a foreign investor is involved, skipping the FEMA reporting leaves a gap that surfaces during the next round's diligence.
Our guide on equity dilution covers the cumulative modelling across rounds.
What else should you know?
Four things come up repeatedly.
Flat rounds don't trigger it. The clause responds to an issue priced below the conversion price, and a flat round leaves that price unchanged.
Investors can hold different terms. Your Series A investor might have broad-based weighted average while your seed investors have none. Later investors frequently negotiate better terms than earlier ones.
Pay-to-play sometimes travels alongside. It penalises existing investors who decline to join a later round, which changes who has an incentive to support you when things get hard.
The charter is not the term sheet. Five words in a term sheet become a page of formula in your articles of association, and most founders never open the second version.
The short version
Anti-dilution isn't a clause you can remove. Investors will have protection in some form, and asking them to drop it entirely isn't a negotiation worth opening.
What you choose is the severity. Push back on full ratchet first, ask for broad-based second, and model the adjusted conversion against your actual cap table.
Then read the version in your charter, because that's the one that operates when a down round arrives.
Key takeaways
On a worked example, full ratchet cost founders around 14% against roughly 0.5% under broad-based weighted average, from the same down round.
Full ratchet resets the conversion price entirely to the new price and ignores round size. It appears in fewer than 5% of deals.
Weighted average adjusts partially and is market standard in India and elsewhere.
Broad versus narrow is worth a fraction of a percentage point. The mechanism is worth considerably more, so negotiate it first.
In Indian rounds, anti-dilution sits inside the CCPS terms as a conversion ratio adjustment, and an adjusted conversion still needs its resolutions and filings.
Frequently asked questions
What is an anti-dilution clause?
A term that adjusts an investor's conversion price if the company later raises at a lower valuation, so their holding converts into more equity shares and their ownership percentage is protected.
What is the difference between full ratchet and weighted average?
Full ratchet resets the conversion price entirely to the new lower price regardless of round size. Weighted average adjusts it partially, using a formula that accounts for the size of the down round and the total share count.
Which anti-dilution protection should a founder accept?
Broad-based weighted average. It is market standard in India, and most standard-form term sheets default to it. Full ratchet is rarely justifiable at seed or Series A.
What is the difference between broad-based and narrow-based?
Broad-based counts all outstanding shares, including options, warrants, convertibles, and the ESOP pool. Narrow-based counts only outstanding preference shares. The larger denominator in broad-based produces less founder dilution.
Can anti-dilution be removed from a term sheet?
Rarely. Investors will have protection in some form. What is negotiable is the mechanism, and that is where founders should spend their leverage.
Do flat rounds trigger anti-dilution?
No. The clause is triggered by an issue below the conversion price, so a flat round leaves the conversion price unchanged.
How does anti-dilution work in an Indian round?
It sits inside the CCPS terms as an adjustment to the conversion ratio between preference shares and equity shares, rather than in a separate instrument.